Why Every Parent of a Child with Special Needs Needs More Than a Will
For most Florida parents, preparing a will is an important part of responsible estate planning. For the parent of a child with a disability, however, a will may be only one piece of a much larger puzzle.
A well-drafted special needs plan must answer questions that extend far beyond who inherits the parents’ assets:
- Who will make decisions if the child cannot make them independently?
- Who will manage an inheritance?
- What happens if the child unexpectedly receives money in his or her own name?
- How will Supplemental Security Income (SSI), Medicaid and other public benefits fit together with family resources?
- Who will understand the child’s routines, medical history, preferences and support network after the parents are gone?
These are not questions that can ordinarily be answered by a simple will.
For families of individuals with disabilities, effective Florida special needs planning should instead be thought of as the creation of a coordinated system — one designed to protect eligibility for important public benefits while also providing private resources, appropriate decision-making support and continuity of care throughout the individual’s lifetime.
The Third-Party Special Needs Trust: Planning Before the Inheritance Arrives
One of the central components of many special needs estate plans is a third-party special needs trust.
The name describes where the money comes from. A third-party trust is funded with assets belonging to someone other than the individual with a disability — typically parents, grandparents or other family members.
Instead of leaving an inheritance directly to a child who receives or may later need means-tested public benefits, parents can direct assets to a properly drafted special needs trust. The trustee can then use those assets for the beneficiary in ways intended to supplement, not unnecessarily replace, the benefits and services available through government programs.
This distinction can be extremely important. SSI and certain Medicaid programs have financial eligibility rules. An outright inheritance may therefore create an eligibility problem that could have been avoided through advance planning.
Parents sometimes attempt to solve this problem by providing in their wills that the child’s inheritance will pass into a special needs trust. While a testamentary special needs trust may be appropriate in some circumstances, I frequently prefer to consider creating the third-party special needs trust during the parents’ lifetimes.
Why?
An inter vivos, or lifetime, trust creates a receptacle that already exists. Parents can coordinate their estate plans with it, but so can grandparents and other relatives.
It also creates opportunities to:
- direct life insurance and appropriate beneficiary designations to the trust;
- select the trustee;
- establish administrative provisions; and
- begin developing the infrastructure that may ultimately survive the parents.
It can also avoid unnecessarily requiring assets intended for the special needs trust to pass through probate merely to establish the trust after death.
Most importantly, the trust becomes part of the family’s planning architecture now rather than something that springs into existence only after a parent’s death.
There is another significant distinction. A properly structured third-party special needs trust generally does not operate under the Medicaid-payback rules applicable to a self-settled special needs trust simply because the beneficiary receives Medicaid. The assets belonged to the parents or other third parties, not to the beneficiary. Federal SSI policy likewise distinguishes trusts funded solely with third-party assets from trusts funded with the individual’s own assets.
That makes preserving the distinction between the family’s money and the beneficiary’s own money critically important.
The First-Party Special Needs Trust: Planning for the Money Nobody Expected
If a third-party special needs trust is already in place, why would the family also need to understand first-party special needs trusts?
Because life rarely follows the estate plan.
A person with a disability may unexpectedly acquire assets in his or her own name. The source might include:
- an incorrectly directed inheritance;
- a personal injury settlement;
- accumulated funds;
- a beneficiary designation that was never updated; or
- another financial event that nobody anticipated when the parents’ estate plan was created.
Once the asset belongs to the individual, simply placing it into the family’s third-party trust generally is not the answer.
Federal law provides a separate planning mechanism commonly called a first-party or self-settled special needs trust, including the trust authorized under 42 U.S.C. § 1396p(d)(4)(A). When the statutory requirements are satisfied, assets belonging to a qualifying individual with a disability can potentially be held in trust without being treated in the same manner as assets otherwise available directly to that individual for purposes of certain means-tested benefits.
But there is an important tradeoff.
Unlike a typical third-party special needs trust, a qualifying first-party special needs trust contains a Medicaid reimbursement requirement. At the beneficiary’s death, remaining trust assets are subject to reimbursement to the state or states for qualifying Medicaid assistance, subject to the applicable rules.
This is one reason families should understand both kinds of trusts. They solve different problems:
- The third-party trust is primarily proactive planning for other people’s money.
- The first-party trust can become a remedial planning tool for the beneficiary’s own money.
Confusing the two, or mixing assets that should remain separate, can have significant consequences.
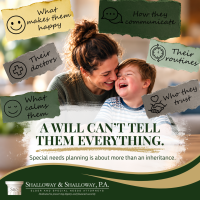
A Trust Cannot Tell the Next Caregiver Everything
Even an exceptionally drafted special needs trust has limitations.
A trust is a legal instrument. It can identify trustees, establish distribution standards, grant administrative powers and describe the purposes for which assets are to be used.
It is generally not the place to memorialize every detail a parent has learned over 20 or 30 years about caring for a son or daughter.
That is the role of a Letter of Intent.
A Letter of Intent is generally not a substitute for the family’s binding legal documents. Instead, it provides something equally valuable: institutional memory.
Imagine a parent trying to explain to a future caregiver everything that makes his or her child unique:
- What medications are taken and when?
- Which physicians know the individual best?
- What behaviors signal anxiety or illness?
- What foods are preferred or avoided?
- What sensory issues matter?
- What daily routines provide stability?
- Who are the important relatives, friends, therapists, case managers, clergy or community contacts?
- What recreational activities bring joy?
- What transportation arrangements work?
- What employment or day-program history should be preserved?
And then there are the details that may sound insignificant to a lawyer drafting a trust but can be enormously important to quality of life: how someone communicates discomfort, what bedtime routine works, what music calms him or her, which restaurant is a favorite, or why changing a seemingly minor routine can cause substantial distress.
Parents often carry this information in their heads.
The problem is that someday they may not be available to explain it.
A thoughtfully prepared Letter of Intent allows families to begin transferring that knowledge to the people who may eventually assume responsibility. Unlike a trust, it can and should evolve as the individual’s circumstances change.
Who Will Make Decisions?
Financial planning is only half of the equation. Families must also consider decision-making authority.
When a child reaches age 18, disability alone does not automatically continue a parent’s legal authority to make decisions. The appropriate planning response depends upon the individual’s abilities and circumstances and should include consideration of less restrictive alternatives where they are sufficient.
Florida provides a specialized guardian advocate procedure for certain persons with developmental disabilities. Under Florida Statutes §393.12, a circuit court may appoint a guardian advocate without a traditional adjudication of incapacity when the statutory requirements are satisfied.
Importantly, Florida law directs the court to consider the individual’s unique needs and abilities and to delegate only those decision-making tasks the person lacks the ability to exercise. Existing alternatives, including advance directives, durable powers of attorney and supported decision-making assistance, are also relevant to that analysis.
For individuals who do not fit within the guardian advocate statute or whose circumstances require a different approach, Florida’s traditional guardianship laws may apply.
The planning should begin well before a crisis.
For a minor child, Florida law permits parents to nominate a preneed guardian of the child’s person, property, or both through a written declaration meeting statutory requirements. The parents may also designate an alternate.
A competent adult may likewise execute a Florida declaration naming a preneed guardian to serve in the event of the adult’s later incapacity. When properly produced in an incapacity proceeding, the declaration creates a rebuttable presumption favoring the designated person, although the court retains responsibility for determining whether that individual is qualified to serve.
The important planning question is therefore not simply:
“Who gets the money?”
It is also:
“Who steps into the parents’ shoes?”
Selecting a Trustee Is Only the Beginning
The person best suited to manage money is not necessarily the person best suited to understand the beneficiary’s day-to-day needs.
That is why sophisticated Florida special needs trusts may consider additional roles.
A trust protector, depending upon the powers granted in the document, can provide oversight or flexibility when circumstances change. Properly drafted provisions might permit a protector to address certain trustee issues, respond to changes in law or resolve problems that could not reasonably have been anticipated when the trust was signed.
A trust advisory committee can provide another layer of knowledge and continuity. Family members, professionals or others familiar with the beneficiary may help communicate information about:
- housing;
- care;
- education;
- therapies;
- employment;
- recreation; and
- quality-of-life issues.
These arrangements require careful drafting. Adding more people does not automatically produce better administration. Roles, authority, succession and potential conflicts should be considered in advance.
But they illustrate an important principle: special needs planning is about creating a durable decision-making structure, not simply drafting a trust.
Public Benefits and Private Funds Should Work Together
Another common planning mistake is treating public benefits and family resources as competing alternatives.
They should instead be considered together.
Depending upon the individual, the benefits landscape may include:
- Supplemental Security Income (SSI);
- Social Security Disability Insurance;
- Disabled Adult Child benefits;
- Medicare;
- Medicaid;
- Florida Medicaid waiver programs; and
- other federal, state or local services.
Eligibility rules differ considerably among programs, and not every benefit is means-tested.
The goal should not necessarily be to preserve a government benefit at any cost. Nor should families assume that private money should pay for everything simply because resources are available.
The better question is:
What combination of public benefits, trust resources, family resources, insurance and community services can provide the greatest long-term security and quality of life?
That analysis should be revisited periodically.
For example, a child receiving SSI and Medicaid at one stage of life may later become eligible for Social Security benefits on a parent’s earnings record. Medicare eligibility may eventually enter the picture. Medicaid waiver services may affect housing and care decisions. Changes in family finances, trustee circumstances or the beneficiary’s medical and functional needs may require the plan to evolve.
Special needs planning therefore cannot be treated as a document that goes into a drawer for 20 years.
The Most Important Asset May Be the Plan Itself
Consider two families.
Both have a child with significant lifelong disabilities. Both parents have wills. Both intend to divide their estates fairly among their children.
The first family’s plan stops there.
The second family has:
- established a third-party special needs trust;
- coordinated beneficiary designations with it;
- planned for what would happen if assets unexpectedly came into their child’s own name;
- evaluated SSI, Medicaid and other benefits;
- addressed decision-making authority;
- nominated appropriate successors;
- prepared a Letter of Intent explaining the child’s medical, social and personal world;
- ensured the trustee knows who to contact; and
- included mechanisms for adapting to circumstances the parents cannot predict.
Both families have wills.
But only one has built a special needs plan.
That distinction becomes increasingly important as parents age. The objective is not merely to transfer wealth. It is to transfer knowledge, responsibility, advocacy and resources from one generation to the next.
Planning Should Begin While Parents Can Still Lead It
Perhaps the greatest advantage of planning early is that parents remain available to build the team.
They can:
- introduce a future trustee to their child;
- identify potential guardian advocates or other decision-makers;
- teach siblings what responsibilities they are, and are not, expected to assume;
- organize benefit records, medical information and financial resources;
- create and update the Letter of Intent; and
- observe whether the structure they have created actually works.
For attorneys, financial advisors, accountants, care managers, therapists, health-care professionals and others serving families affected by disability, this also presents an important issue-spotting opportunity.
When a parent says, “We already have a will,” the next question should often be:
“What else is in the plan?”
A comprehensive Florida special needs plan may require coordination among:
- estate planning;
- special needs trusts;
- public benefits;
- guardianship or guardian advocacy;
- tax and financial planning;
- beneficiary designations;
- trustee selection; and
- long-term care planning.
No single document accomplishes all of those objectives.
The goal is to create a structure capable of continuing what parents have spent a lifetime doing themselves: protecting their child, advocating for appropriate services, managing resources wisely and preserving the best possible quality of life.
That takes much more than a will.
About Shalloway & Shalloway, P.A.
Shalloway & Shalloway, P.A. assists individuals with disabilities, their families and the professionals who advise them with special needs trusts, public-benefits planning, Medicaid planning, guardianship and guardian advocacy counseling, estate planning and related long-term-care issues throughout Florida.
Families and professionals who identify a potential Florida special needs planning issue should seek individualized advice before changing beneficiary designations, transferring assets, establishing or funding a trust, or taking other action that could affect eligibility for public benefits.
This article is intended for general educational purposes and does not constitute legal advice. Special needs trust, Medicaid, SSI and guardianship rules are highly fact-specific and may change. Individuals should obtain advice regarding their particular circumstances from qualified counsel.